"Tell me the difference between stupid and illegal, and I'll have my wife's brother arrested." — The Big Short
Three kinds of statement follow:
- Documented facts from Signa Prime's audited accounts and the MSCI Real Capital Analytics transaction record.
- Findings of the Vienna insolvency court and the administrators.
- Starboard's own inference, which covers every modelled figure here.
Nothing asserts intent.
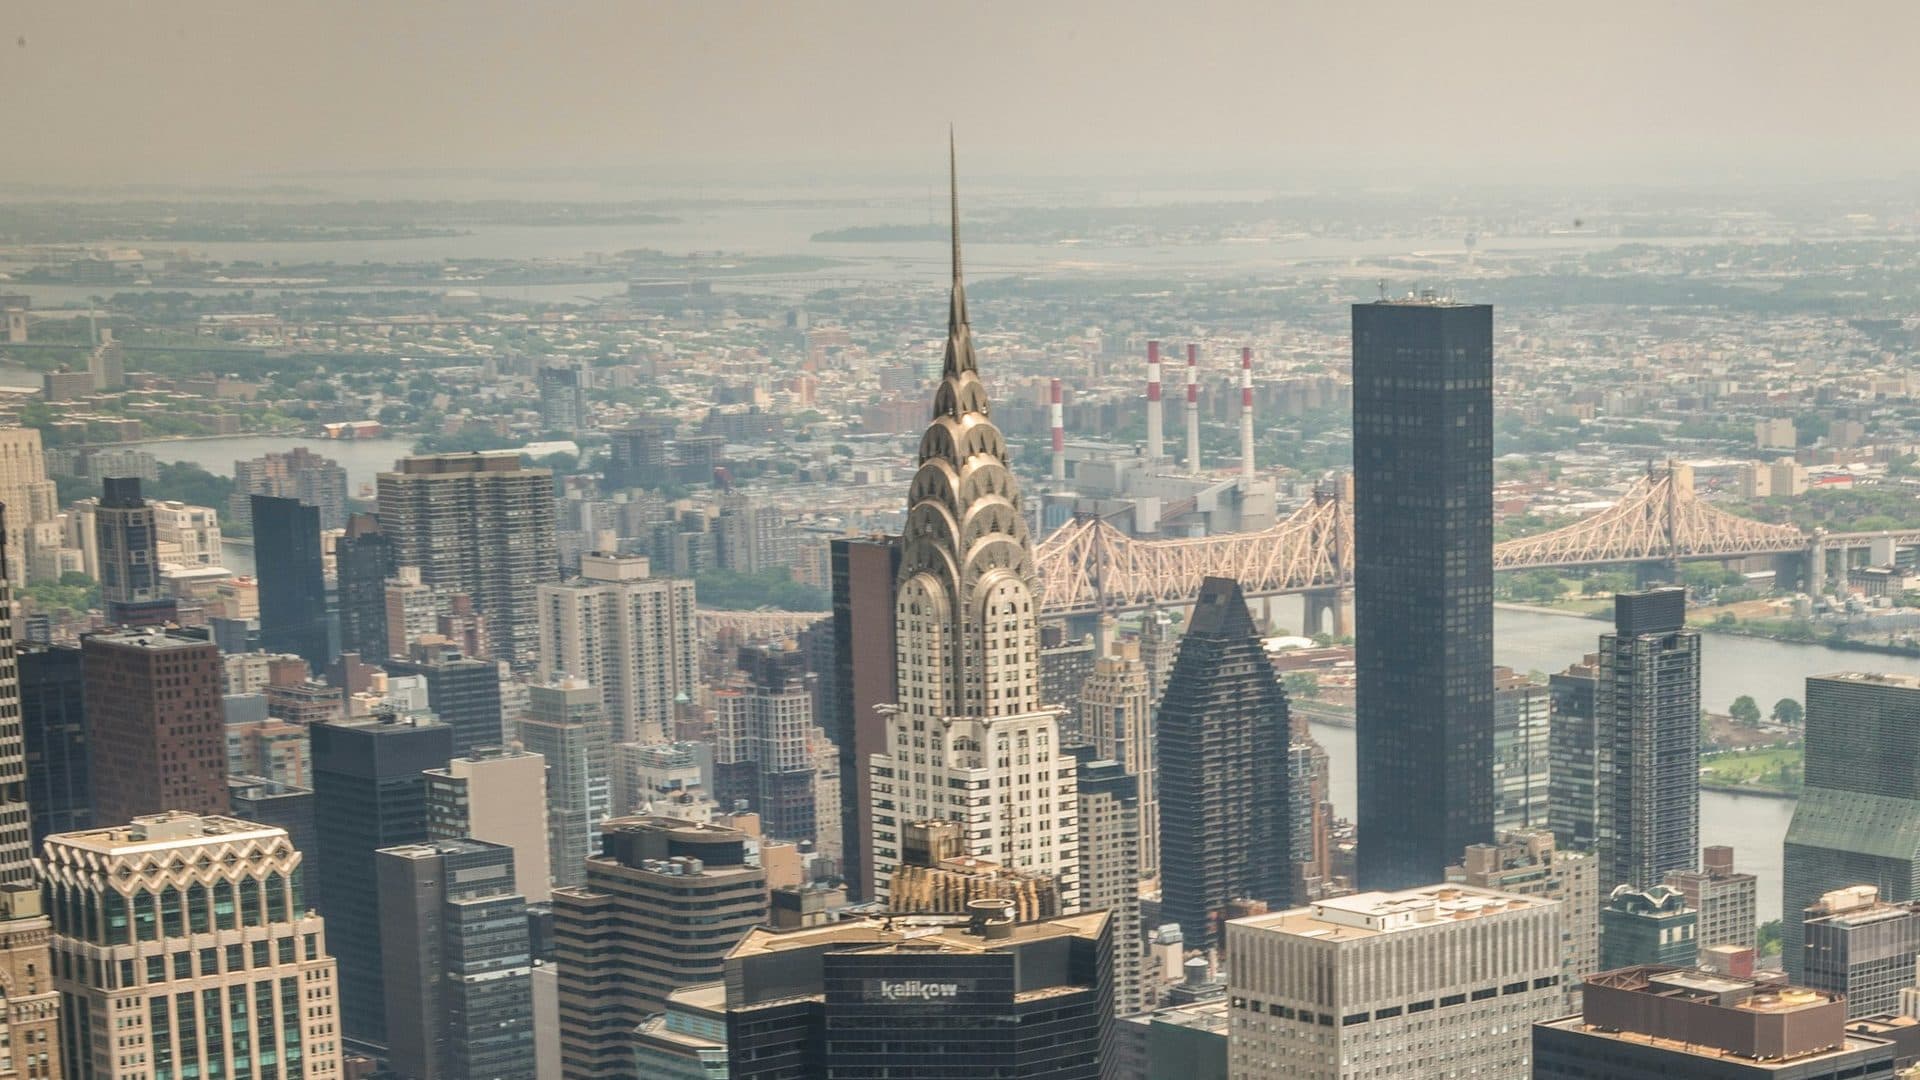
The tower on the masthead is one of the purchases. Signa and RFR Holding bought the Chrysler Building in 2019, and Signa's stake in it peaked at 50%. The record carries two Chrysler interests.
Signa paid 1.56× the local market, and more where it spent most
Of 197 Signa purchases from 2014 onward with a usable price per square foot, 170 matched a benchmark. The benchmark is the local market median, and it is deliberately specifically scoped: the median price per square foot of the 10 to 20 most comparable recorded sales, comparability being the same year, country, property type and kind of location. A purchase counts as matched when that comparable set exists at all: the 27 that found none carry no premium and drop out of every ratio here. The median paid 1.56× that local benchmark, the middle half sat between 1.00× and 2.73×, and 72.4% paid above the local median. Weighted by the money spent the premium rises to 1.96×: the largest cheques carried the largest premiums. The two heaviest years bracket the pattern. 2018 ran 74 purchases and €4.07bn at a 1.42× median; 2019 ran 64 purchases and €3.87bn at 2.73×. The 2019 peak needs a caveat: around 40 Galeria Kaufhof stores bought that year carry one portfolio-allocated price of USD 479.63 per square foot spread across them, so a single allocation drives the year, which is also why the upper quartile equals the 2019 median exactly.
Show every year as a table
| Year | Matched purchases | Median premium | All purchases | Volume |
|---|---|---|---|---|
| 2013 | 5 | 1.17× | — | — |
| 2014 | 2 | 1.64× | — | — |
| 2015 | 1 | 0.97× | — | — |
| 2016 | 4 | 0.79× | — | — |
| 2017 | 8 | 1.80× | — | — |
| 2018 | 66 | 1.42× | 74 | €4.07bn |
| 2019 | 56 | 2.73× | 64 | €3.87bn |
| 2020 | 15 | 1.07× | — | — |
| 2021 | 1 | 2.43× | — | — |
| 2022 | 3 | 0.54× | — | — |
| 2023 | 9 | 2.56× | — | — |
The three 2023 Galeria Kaufhof purchases are the best-documented of the late buying, and all clear the same USD 431 benchmark: Hohe Strasse in Cologne at 3.21×, Frankfurt Hauptwache at 2.84× and Dusseldorf at 2.56×. The record values those buildings at €429m, €294m and €221m, but what Signa bought in each case was a 20% interest, roughly €86m, €59m and €44m. All three prices are graded appraised, which is to say valued rather than market-cleared.
Remove the landmarks and the premium does not fall
Every ratio above is like for like: the yardstick is the local market as it stood when Signa bought, read off the 10 to 20 most comparable sales, drawn from a pool that typically holds 208 recorded ones. What those keys do not control for is building age, size or quality.
Benko's objection throughout was that many of these buildings had no peers: a flagship department store on a capital city's principal street, or a building begun in 1576 on Munich's Marienplatz, is a sample of one. We tested that rather than arguing with it. Twenty-four purchases carry landmark or trophy character on their face: KaDeWe, Oberpollinger, Alsterhaus, the Alte Akademie, the Postsparkasse, the Kaufmannshaus, the Alsterarkaden, Sevens, the Karstadt and Galeria Kaufhof flagships, Upper West in Berlin, the Globus stores, both Chrysler Building interests, and the future Elbtower, a quarter of the money spent between them.
Removing the landmark properties does not lower the premium. The median on the remaining 168 purchases is 1.69× against 1.66× for the full matched set, the share above the local median unchanged at 72%, and weighted by the money spent the figure moves from 2.00× to 2.02×. Those moves are inside the noise of the estimate: the supportable reading is that the premium does not fall, not that removing the landmarks raises it.
The landmarks ran at a 1.45× median, below the rest of the programme, and six of the twenty-four priced below their local yardstick outright. The overspend sits in land, and in very little of it: eleven development sites, whose square footage is what the buyer intends to build rather than what stands, ran a 2.19× median and 4.51× weighted. Those eleven account for 2.7% of everything Signa spent, so the programme's sharpest premiums sit on its smallest slice of money, the Elbtower alone at 5.63×. With both screens applied, 158 standing, non-landmark buildings run 1.58× median, 70.9% above local and 1.97× weighted, below the full matched set rather than above it. The premium is not an artefact of unique assets, and not one of land.
Show the exclusion test as a table
| Purchase set | Purchases | Share of the money spent | Median premium | Above local median | Weighted by spend |
|---|---|---|---|---|---|
| All matched purchases | 192 | 100.0% | 1.66× | 72.4% | 2.00× |
| The landmark assets alone | 24 | 25.0% | 1.45× | 75.0% | 1.94× |
| Development land alone | 11 | 2.7% | 2.19× | 90.9% | 4.51× |
| Excluding the landmarks | 168 | 75.0% | 1.69× | 72.0% | 2.02× |
| Excluding landmarks and land | 158 | 73.3% | 1.58× | 70.9% | 1.97× |
A book that ran ahead of the market, and fastest in 2017
In 2017 and 2019 the valuation entry exceeded the entire net profit: a €1,001.9m fair-value gain inside €805.1m of net profit, and a €933.3m gain inside €909.1m. The operating business lost money before the mark in both years. Cash flow from earnings was flat while the book nearly doubled from €7.07bn to €13.17bn. Interest paid was €289.3m in 2019 against €231.1m of cash earnings, and the €201m dividend was 87% of the year's cash generation. Across 2017 to 2021 Prime paid roughly €1.9bn of interest and dividends against roughly €1.6bn of rental revenue.
Show the audited figures as a table
| Signa Prime, EUR m | 2017 | 2018 | 2019 |
|---|---|---|---|
| Fair-value gain on investment property | 1,001.9 | 324.1 | 933.3 |
| Net profit | 805.1 | 421.8 | 909.1 |
| Cash flow from earnings | 163.7 | 229.2 | 231.1 |
| Dividend paid | 72.4 | 120.4 | 201.0* |
| Net profit without the mark | −€196.8m | +€97.7m | −€24.2m |
| Interest paid | — | — | 289.3 |
Against that, our market-implied path. On 2014 = 100 the index runs 118.4 in 2017, 136.7 in 2019, a peak of 166.1 in 2021, then 158.1, 153.3 and 147.1 through 2024. Indexed forward from its own year, the held stock carries an implied uplift over cost of +19.5% in 2019 (€9.65bn against €11.53bn) and +45.2% at the 2021 peak (€8.41bn against €12.22bn), then +35.7% in 2022 and +29.5% in 2023. Prime's book ran ahead of that path, and by most in 2017: dividing the audited fair-value gain by the book gives roughly 16.5% on the year against about 6% for the index. 2019 is close to the index, about 7.6% against 7.5%, and 2018 runs below it. On the MSCI-visible stock alone the gap at 2021 is on the order of €6bn. Those are different perimeters, though: the stated figure covers the group while the held stock is only what the record shows, so that gap is an unexplained difference rather than a measure of overmarking.
Show the index and the implied path as a table
| Year | Repeat-sales index, 2014 = 100 | Held stock at cost | Market-implied value | Implied uplift over cost |
|---|---|---|---|---|
| 2014 | 100.0 | — | — | — |
| 2017 | 118.4 | — | — | — |
| 2019 | 136.7 | €9.65bn | €11.53bn | +19.5% |
| 2021 | 166.1 | €8.41bn | €12.22bn | +45.2% |
| 2022 | 158.1 | — | — | +35.7% |
| 2023 | 153.3 | — | — | +29.5% |
| 2024 | 147.1 | — | — | — |
Under modest write-downs the balance sheet had broken before the rate shock
Prime defined its loan-to-value ratio as bonds plus bank liabilities, including debt on assets held for sale, over the balance sheet total, which the accounts label gross asset value. The denominator is the thing being revalued: bank debt grew 59%, from €4.37bn in 2017 to €6.93bn in 2019, and the reported ratio still fell, from 50% to 46%.
Show the leverage grid as a table
| Year | Reported loan-to-value | Debt / property at book | −20% | −30% | −40% |
|---|---|---|---|---|---|
| 2017 | 50% | 61.8% | 77.3% | 88.3% | 103.0% |
| 2019 | 46% | 52.6% | 65.8% | 75.2% | 87.7% |
| 2022 | 46.9% (press-sourced) | 75.9% | 94.9% | 108.4% | 126.5% |
Valuing the portfolio as a multiple of its rental revenue is a cross-check independent of our index. At 20–25× 2022 revenue of €465.86m, the range Green Street applies to comparable listed office portfolios, the portfolio is worth €9.3–11.7bn against €10.8bn of debt: 93–116%. Only at 30.5× does it come back to 76%.
Under this stress test the ratio crosses any ordinary bank covenant in 2022, and on a 20% write-down it had already crossed in 2017. This is a stress test rather than a market mark: our own index has the held stock above cost through 2023, and the revenue multiple in the lower panel is the stronger support. An administrator's filing dates Signa Prime's material insolvency to 31 March 2022, inside that window rather than ahead of it, while Signa Holding's administrator puts Holding's own insolvency at around November 2022. Our inference is that the balance sheet was broken before the rate shock and that the shock removed the ability to carry it. Signa Holding filed for insolvency on 29 November 2023, and its restructuring plan offered creditors a 30% quota against a stated gross asset value of €19.3bn.
What negative rates hid
The correlation between the European Central Bank deposit facility rate and Signa's annual buying is −0.35: buying rose as the rate fell. The regime statement is the stronger one. The deposit rate sat at or below zero from mid-2014 to mid-2022, and 73% of the €14.1bn was spent between 2014 and 2020 with the rate at or below −0.09%. The exceptions are late, and they are the purchases this article dwells on: the Elbtower site closed in August 2022 at a zero rate, Gänsemarkt 50 that November at 1.5%, and roughly €0.76bn of 2023 buying, including the three Galeria Kaufhof flagships, closed with the rate between 2.5% and 4%.
The turn shows in three series at once. The deposit rate went from +0.08% average in 2022 to 3.31% in 2023. European commercial real estate volume fell from USD 385.4bn in 2021 to USD 198.6bn in 2023. Signa flipped from net buyer to forced seller: 23 sales and €2.76bn in 2023, then 34 sales, €3.49bn and zero purchases in 2024. Nearly all of the reported value growth was repricing rather than income, which makes the entry premium and the mark one problem: a book carried on multiples has no cushion when the multiple moves.
The takeaway from this investigation is that the accounts gave the answer before the market did: a book outrunning its own cash generation, dividends paid out of revaluations, and leverage that only modest write-downs put through covenant. You could use the Starboard platform today to run those same checks on a firm you hold, or one you are about to back.
Data appendix: method
Transaction data. The MSCI Real Capital Analytics record returns 530 rows naming Signa, dated 2004 to 2026, of which 197 are purchases from 2014 onward with a usable price per square foot. Prices ship in US dollars, converted at the daily European Central Bank reference rate on each transaction's status date.
Benchmarking. The local market median is the median price per square foot of the 10 to 20 most comparable recorded sales. Comparability is set on four keys: year of sale, country, property type and whether the location is central. The ratio of Signa's price to that median is the premium. 170 of 197 purchases matched, their comparables drawn from a pool that typically holds 208 recorded sales; restricting to purchases with at least five comparable sales moves the median by three hundredths. The 170 matched include five 2013 purchases carried in Figure 1, so the matched set runs from 2013 while the 197 priced purchases are counted from 2014 onward. An independent re-pull of the record in September 2026 returns higher counts, 229 priced purchases from 2014 onward and 216 matched on this benchmark. The figures in this article rest on the original extract, and the difference sits in filters the underlying research note does not document.
Exclusion test. Because those keys do not control for uniqueness, we ran the premium again with the assets most open to the objection removed: 24 landmark or trophy purchases identified by name, and 11 development-land purchases whose area is prospective rather than standing. Both screens ran against the full matched set from 2013 onward, recomputed end to end, which is why that test reports 192 matched purchases at 1.66×.
Price grades. Every row in the 530-row record carries a grade: 271 portfolio allocations, 124 estimated, 80 approximate, 31 confirmed, 14 unverified market talk and 10 appraised. Only three of those confirmed prices fall inside the 197 priced purchases from 2014 onward, so every premium figure rests predominantly on prices graded allocated, estimated or approximated.
Value path. The repeat-sales index draws on 1,783 pairs, run separately for retail and office and blended 79.2/20.8 at Signa's own mix. A linked median price-per-square-foot index was built first and rejected for volatility. Each purchase is indexed forward from its own year and dropped on the year the property sold.
Leverage. We recomputed the ratio holding debt at face value and cutting the carrying value of investment property by 0%, 20%, 30% and 40%, in place of Prime's definition. The revenue-multiple cross-check applies 20–25× against Signa's own appraisers at 41× for offices and 30× for hotel and retail.
Dropped test. The scope included a transfer-pricing step-up test on intra-group transfers. Every Signa party in the record resolves to one flat label, Signa Group: there is no Prime, Development or subsidiary layer, and no row carries Signa on both sides of a trade. We did not substitute a proxy.
What this does not show
Six limits, all material. The entry premium describes how Signa bought, and it does not on its own separate a failing buyer from a prudent one: run the same screen across European buyers and large institutional funds with no solvency problem score at or above Signa, while several firms that later failed score below the market. The accounts, not the premium, are what carry the argument. The premium distribution is also one of estimated prices rather than settled ones. The record carries a cap rate on 17 rows and on only one of the purchases, so there is no income-yield route through the transaction data. Every Signa party resolves to a single flat label, so the transfer-pricing step-up test cannot be run. 2020 has no audited anchor available to us, and the 2021 and 2022 figures rest on press reporting rather than statements we have read. And the repeat-sales index is our construction rather than a published series, so the value path and the loan-to-value grid built on it are modelled. None of this touches the audited fair-value, profit, cash-flow and dividend figures, which are the spine of the argument.
The first of those limits is the one worth seeing rather than reading. Every premium in this article rests on what MSCI grades each price, and the grade that means a settled, verified consideration covers 31 rows of the record and only three of the priced purchases the premium is built on.
Sources
Audited. Signa Prime Selection AG, audited consolidated financial statements under International Financial Reporting Standards, FY2018 with 2017 comparatives, filed with the Luxembourg Stock Exchange, where Prime's bonds were listed: source for the 2017 and 2018 fair-value gains, net profit, cash flow from earnings, dividends, bank debt and reported loan-to-value ratio. Signa Prime Selection AG, audited consolidated financial statements FY2019, same filing route: source for the 2019 fair-value gain of €933.3m, net profit of €909.1m, cash flow from earnings of €231.1m, interest paid of €289.3m, investment property of €13.17bn, bank debt of €6.93bn and the 46% reported loan-to-value ratio.
Third-party data. MSCI Real Capital Analytics transaction records, accessed September 2026: all Signa purchases and sales, prices, square footage, dates, parties, locations and price grades, and the comparable-sale universe behind every benchmark median. European Central Bank deposit facility rate, and the US dollar/euro daily reference rate, from the US Federal Reserve's economic data service, for currency conversion. Green Street multiple range for comparable listed office portfolios, 20–25×, used in the capitalisation cross-check.
Press-sourced. Press reporting of the 2019 Chrysler Building purchase by Signa and RFR Holding and of Signa's 50% stake in it. Press reporting of Signa Prime's filings with the Austrian companies register, the Firmenbuch, for the 2021 and 2022 figures, including Bloomberg via Die Presse on the €201m dividend for 2019: source for the €18.8bn stated gross asset value at end-2021, the €225m dividend for 2021, 2022 revenue of €465.86m, debt of €10.8bn, investment property of €14.23bn and the 46.9% reported ratio. Not audited figures we have read.
Court and administrator. Vienna insolvency court findings and administrators' reports: the 29 November 2023 insolvency filing by Signa Holding, the administrator's dating of Signa Prime's material insolvency to 31 March 2022 and of Signa Holding's own to around November 2022, the 30% creditor quota offered in Holding's restructuring plan against a stated gross asset value of €19.3bn, and Benko's November 2012 bribery conviction, upheld by the Supreme Court in 2013.
Our estimates. Reasonable inference. The entry premium ratios at every level, the repeat-sales index and every market-implied value derived from it, the €6bn gap at 2021, the write-down stress test on loan-to-value, the 93–116% cross-check, the exclusion test, the −0.35 correlation and the rate-regime shares are all Starboard's construction on the sources above: modelled, not reported. The insolvency-window conclusion is our inference set against the administrators' dating; the inference is ours, not theirs and not the court's.
Figures are aggregates of licensed MSCI Real Capital Analytics data, prepared by Starboard Research. The transaction record was accessed September 2026; every ratio, index and leverage figure is Starboard's estimate on the sources above and is not audited. Header photograph: midtown Manhattan from the Empire State Building, the Chrysler Building standing against the East River and the Queensboro Bridge, by Eddie Mark Blair on Unsplash. The Chrysler Building leasehold is one of the named purchases in Figure 2.